
Introduction
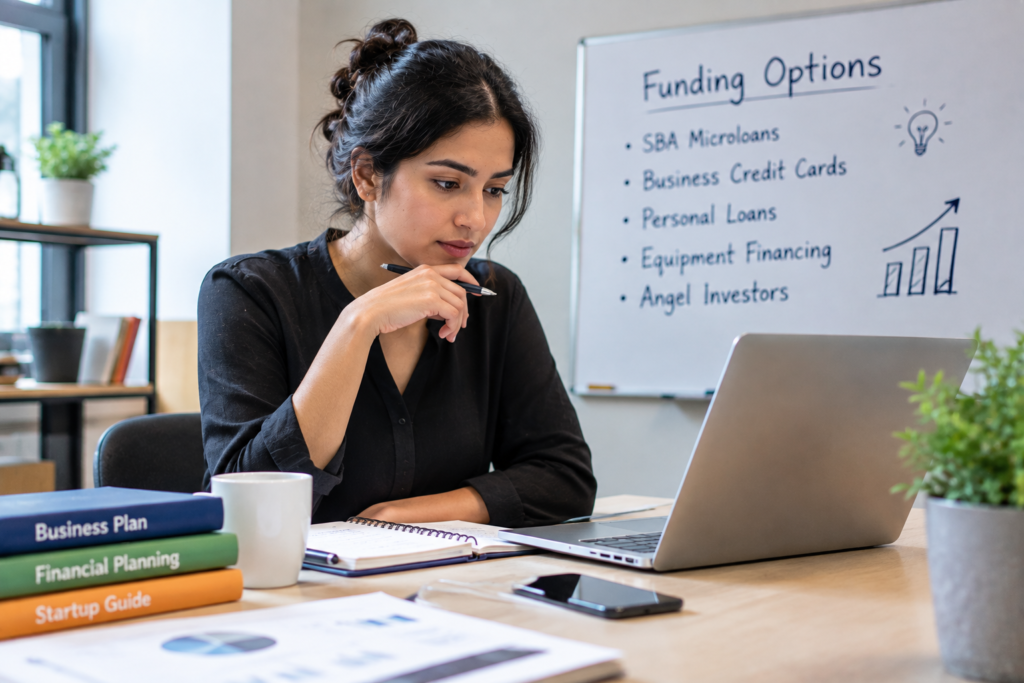
Every new business hits the same wall at some point: bills need paying equipment needs buying and the bank account does not have the sales history a traditional lender wants to see. Business loans with no revenue sound like a contradiction since lenders typically want proof a borrower can repay before handing over cash. Yet a real if narrower market exists for founders who need capital before their business has generated meaningful income.
This situation is more common than it might seem. A founder might have just left a corporate job secured a lease ordered inventory and hired a first employee all before a single sale closes. Someone launching a service business might need working capital for licensing insurance or equipment before booking their first client. In both cases the founder needs money now but the revenue lenders usually require simply isn’t there yet. A seasonal business like a landscaping company gearing up before its first spring contracts faces a similar timing gap needing trucks and equipment months before cash starts coming in.
This guide breaks down what’s actually available for founders in this position how each option works what lenders look at instead of revenue and how to improve the odds of approval. None of this is financial advice tailored to any specific situation and anyone considering these options should review terms carefully and talk to a qualified financial or legal advisor before signing anything.
Why Revenue Matters So Much to Traditional Lenders
Understanding why banks focus so heavily on revenue helps explain why business loans with no revenue are harder to find and typically come with different terms. Traditional lenders evaluate risk primarily through cash flow since consistent revenue demonstrates a business can actually generate the income needed to make loan payments on schedule.
Without that track record a lender has far less data to predict whether a borrower can repay. This is why banks and credit unions which tend to offer the most competitive rates are usually the hardest source of funding for a pre-revenue business. Their underwriting models are built around historical financial statements tax returns and bank statements showing a pattern of income over time.
This doesn’t mean funding is impossible. It means the type of lender the underwriting criteria and the cost of capital shift significantly once revenue history is missing from the equation. Founders in this position typically need to look toward alternative lenders personal financial backing or funding sources that evaluate factors other than business revenue entirely. Recognizing this shift early saves considerable time since applying repeatedly to lenders whose underwriting model simply isn’t built for pre-revenue businesses tends to produce nothing but rejections and wasted effort.
What Lenders Look At Instead of Revenue
When a lender can not rely on business revenue they shift focus to other indicators of repayment ability. Personal credit score becomes one of the most heavily weighted factors since it reflects how an individual has managed debt obligations in the past independent of the new business’s performance.
Personal income and assets outside the business also matter considerably. A founder with a strong personal income from another source significant savings or valuable collateral presents less risk even without business revenue because repayment does not depend entirely on the new venture succeeding immediately.
Time in business industry experience and the strength of the business plan itself can influence approval too particularly with lenders who specialize in early-stage funding. A founder with relevant industry background and a clearly documented plan for reaching profitability presents a more credible case than someone without that context even though neither has business revenue yet to point to.
SBA Microloans and Early-Stage Government Programs
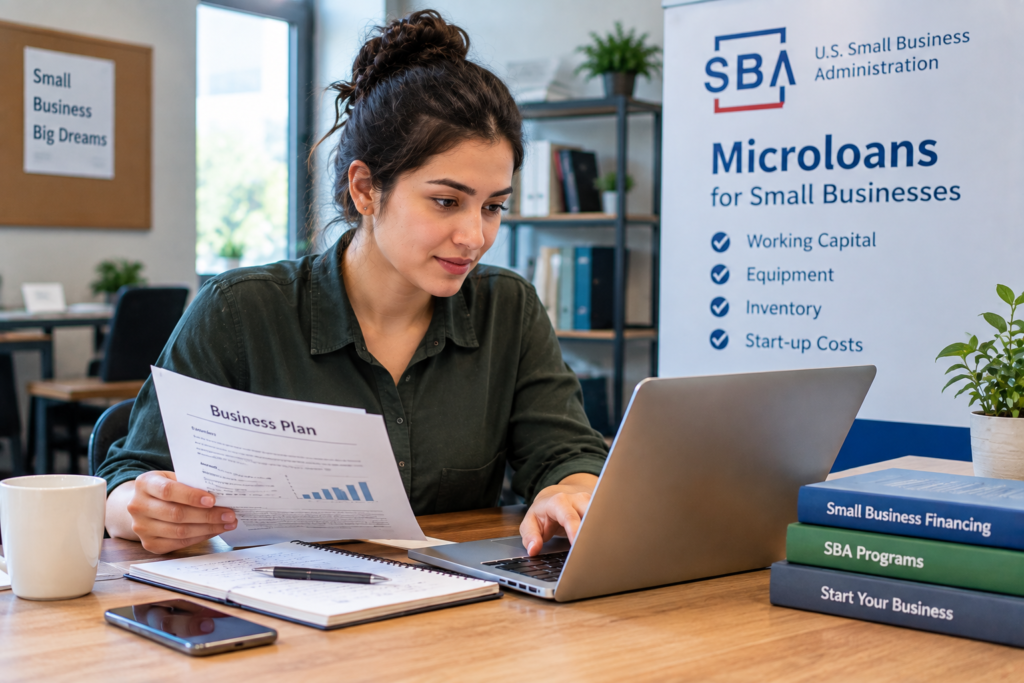
The U.S. Small Business Administration offers several programs relevant to founders seeking business loans with no revenue even though the SBA itself does not directly lend money in most cases. SBA microloans distributed through nonprofit community lenders are specifically designed for smaller funding needs and tend to have more flexible underwriting than traditional bank loans since these lenders often focus on borrowers who don’t fit conventional bank criteria.
These loans typically max out at a modest amount which limits their usefulness for larger funding needs but makes them a realistic option for founders needing capital for initial inventory equipment or working capital. Approval still depends on factors like personal credit a business plan and sometimes collateral but revenue history carries less weight than it would with a traditional bank loan.
Community Development Financial Institutions often working alongside SBA programs frequently serve borrowers overlooked by traditional banks including newer businesses without established revenue. These organizations often prioritize community impact and founder potential alongside pure financial metrics making them worth researching for anyone in this position.
Business Credit Cards as a Practical Alternative
For smaller funding needs a business credit card often provides more accessible capital than a formal loan when revenue history doesn’t exist yet. Approval for many business credit cards relies primarily on the applicant’s personal credit score rather than business financials making this one of the more accessible forms of business loans with no revenue in practice even though it’s technically a different funding structure.
Interest rates on business credit cards tend to be higher than traditional loans which makes them better suited for short-term needs that can be paid off relatively quickly rather than long-term capital requirements. Used carefully though a business credit card also helps build a business credit profile which can improve access to better financing options once the company has some operating history.
Many business credit cards also offer introductory zero-interest periods which can provide meaningful breathing room for a new founder managing early expenses before revenue starts flowing in consistently. Reading the fine print on when that introductory rate expires matters considerably since a jump to a high ongoing rate can create real financial strain if the balance isn’t managed carefully.
Personal Loans Used for Business Purposes
Some founders turn to personal loans rather than business-specific financing when their business lacks the revenue history traditional lenders require. Because these loans are underwritten based on personal credit and income rather than business performance they can be more accessible for a founder with strong personal financial standing even if the business itself has no revenue yet.
This approach carries real trade-offs worth understanding clearly. Personal loans put personal credit and depending on the loan type personal assets directly on the line for a business obligation blending personal and business financial risk in a way that many advisors caution against. If the business struggles the personal financial consequences fall directly on the founder rather than being contained within a business entity.
Founders considering this route should weigh it carefully against other available business loans with no revenue since the personal risk exposure is meaningfully different from most business-specific lending options even when the dollar amounts look similar on paper.
Equipment Financing and Asset-Based Lending
Certain types of financing rely less on revenue history because the loan itself is secured by a specific valuable asset. Equipment financing for example uses the purchased equipment as collateral which reduces lender risk regardless of the business’s revenue history since the lender can recover the asset if payments stop.
This makes equipment financing a genuinely useful option for businesses needing specific machinery vehicles or technology before generating revenue. Approval still typically considers personal credit and some baseline business information but the collateral itself does much of the work that revenue history would normally provide in a traditional underwriting process.
Asset-based lending more broadly extends this same principle to other valuable business assets including inventory or accounts receivable in cases where a business does have some transactions but not enough consistent revenue to qualify through standard channels. This category sits at an interesting middle point useful for founders with some activity but not yet enough to satisfy traditional cash-flow-based underwriting.
Friends Family and Angel Investment as Alternatives to Debt
Not every funding gap needs to be filled with a loan. For founders without business revenue raising capital from friends family or angel investors avoids the debt repayment pressure entirely since this funding typically comes in exchange for equity or in some structured arrangements a defined repayment plan agreed upon privately rather than through formal lending underwriting.
This path requires its own kind of discipline. Clear written agreements even among close family prevent the kind of misunderstandings that can damage both a business relationship and a personal one. Founders should treat these arrangements with the same seriousness as formal financing documenting terms clearly and being realistic about repayment timelines or expected returns.
Angel investors specifically tend to evaluate the founder the market opportunity and the business model rather than existing revenue since many angel investments happen at exactly this pre-revenue stage. This makes angel funding one of the more natural fits for founders who need capital before their business has generated income though it typically requires giving up equity and a degree of input into business decisions.
Building a Stronger Application Without Revenue to Show
Even without revenue founders can strengthen their case significantly through preparation. A detailed realistic business plan that clearly explains how the funding will be used and how the business intends to reach profitability gives lenders or investors something concrete to evaluate beyond raw financial history.
Personal credit health matters enormously here since it often becomes the primary factor lenders rely on in the absence of business revenue. Paying down existing debt correcting any errors on a credit report and avoiding new credit inquiries before applying can meaningfully improve approval odds and terms.
Providing detailed financial projections backed by researched assumptions rather than optimistic guesswork also helps. Lenders and investors evaluating business loans with no revenue want to see that a founder understands their market their costs and a realistic path forward even if the numbers have not materialized yet. Demonstrating relevant industry experience or previous business success if applicable adds further credibility to an application built around potential rather than existing performance.
Risks and Trade-Offs Worth Understanding Before Borrowing
Financing obtained without revenue history often comes at a real cost whether through higher interest rates personal collateral requirements or equity given up in exchange for capital. Understanding these trade-offs clearly before committing helps founders avoid financial strain that could actually delay the business reaching the revenue stage it needs to become sustainable.
Overborrowing presents a particular risk at this stage. It is tempting to secure as much capital as possible when access is limited but taking on more debt than the business can realistically service once revenue does arrive can create long-term financial pressure that outweighs the short-term benefit of having extra cash on hand early.
Comparing total cost across different funding sources not just the initial amount available matters considerably. A business credit card with a high ongoing interest rate might look accessible initially but become expensive quickly if the balance is not paid down before the introductory period ends. Taking time to compare real costs across options tends to produce better outcomes than accepting the first offer available out of urgency. Building even a rough repayment timeline before signing anything helps founders see clearly whether a given option fits realistically within the business’s expected cash flow once revenue does begin.
Conclusion
Business loans with no revenue exist in more forms than many founders initially realize from SBA microloans and equipment financing to business credit cards personal loans and angel investment. Each option shifts the underwriting focus away from business revenue toward personal credit collateral relationships or sheer potential and each comes with its own cost structure and risk profile.
The right choice depends heavily on the specific funding need the founder’s personal financial situation and how quickly the business expects to generate its own revenue. Careful comparison realistic planning and honest conversations with a qualified financial advisor before committing to any funding source all help ensure the capital raised actually supports the business rather than creating strain it can not yet handle.
FAQs
Can a brand-new business get a loan with absolutely no revenue?
Yes though options are more limited and often come with different terms than traditional business loans. Lenders typically shift their evaluation toward personal credit collateral or the strength of the business plan when revenue history is not available.
What credit score is usually needed for business loans with no revenue?
Requirements vary by lender but many alternative lenders and business credit cards look for a personal credit score in the good to excellent range since personal credit becomes the primary risk indicator in the absence of business revenue.
Are SBA loans available for businesses without revenue?
SBA microloans distributed through community lenders are often more accessible to newer businesses than traditional SBA-guaranteed bank loans though approval still depends on factors like personal credit a solid business plan and sometimes collateral.
Is it better to use a personal loan or a business credit card for a business with no revenue?
It depends on the funding amount and timeline. Business credit cards suit smaller shorter-term needs and can help build business credit while personal loans may offer larger amounts but put personal credit and assets more directly at risk for a business obligation.
Do investors ever fund businesses with no revenue at all?
Yes. Angel investors and some early-stage venture funds regularly invest in pre-revenue businesses evaluating the founder market opportunity and business model rather than existing financial performance.
What documents help strengthen a loan application without revenue history?
A detailed business plan realistic financial projections personal credit and financial statements and any relevant industry experience all help lenders or investors evaluate potential in the absence of an existing revenue track record.
Are interest rates higher for business loans with no revenue?
Generally yes. Lenders offset the added risk of lending without revenue history through higher interest rates collateral requirements or personal guarantees making it important to compare total borrowing costs across available options.